You want to eat your favourite food from your favourite restaurant, but there is the usual tedious task in front of you – from getting ready to arriving at the restaurant through modern-day traffic to waiting for your table.
You suddenly decide to postpone your dine-out plan and eat home-cooked food instead. Available are food ordering options but you still have to pick it up from the restaurant. Hence, eating at home often seems to be a better option after a tiring day at work.
Worry no more because Swiggy has come to the rescue.
Prior to Swiggy, all options available were food ordering services, but Swiggy introduced ordering & delivering food services at your doorsteps – much needed by the customers.
Let us now understand how Swiggy works and makes money by diving deep into the Swiggy business model.
Swiggy Business Model
Just like Grubhub in the USA, Swiggy operates on a hyperlocal on-demand food delivery business model. It aggregates restaurants and organises a delivery fleet that carries each order to the customer’s doorstep. The platform had 27.5 million average monthly transacting users in Q1 FY27.
Owned and operated by Bundl Technologies Private Limited, Swiggy has grown from a unicorn startup into a listed company trading as NSE: SWIGGY. It followed the path paved by Uber and crafted a business model built on a dual partnership. The partners fall into three categories.
Swiggy reports five business segments: food delivery, quick commerce through Instamart, out-of-home consumption, supply chain and distribution, and platform innovations (Q1 FY27 shareholder letter). Instamart booked Rs 7,907 crore of gross order value in Q1 FY27 out of Rs 18,926 crore in consumer-facing gross order value, roughly 42%. Food delivery, the other large vertical, booked Rs 9,490 crore.
Restaurant Partners: These are restaurants that accept orders placed through the Swiggy app and website. Swiggy had 265,800 average monthly transacting restaurant partners in food delivery in Q1 FY27.
Delivery Partners: This is the fleet that collects orders from partner restaurants and delivers them to the customer. Swiggy had 648,000 average monthly transacting delivery partners across the platform in Q1 FY27.
Dark Store Partners: Instamart fulfils its quick commerce orders from 1,171 dark stores across 131 cities.
How Swiggy Works?
Swiggy provides an online platform for ordering from a wide range of listed neighbourhood partner restaurants and has its own fleet of delivery personnel who pick up the orders from the partner restaurants and deliver them to the customers at their doorsteps.
Swiggy works by providing a complete food ordering and delivery solution that connects the existing neighbourhood restaurants with the urban foodies proving to be beneficial for both.
You can open the Swiggy application on your mobile phone or visit the Swiggy website, and you will find a whole list of restaurants to order from.
Once the restaurant is selected and the order placed, the restaurant which has its own Swiggy application receives the order details and starts preparing the order.
A broadcast signal is then sent to all the drivers in the vicinity who have their own driver applications. Those willing to accept the order can choose to accept and deliver it.
Like other on-demand delivery startups, Swiggy also integrated the Google Maps API, which lets the customers know where their order is and the amount of time it will take for their order to get delivered in real-time.
How Swiggy Makes Money?
Swiggy’s business model has made Swiggy an early mover in the food service space in India and has had a set base model on which its business is based, but it has started earning revenues from other related avenues ever since it established itself.
The following are the different sources that Swiggy makes money from:-
Commissions
Swiggy typically charges restaurants a commission on each order. Base commissions usually sit between 17% and 25%, according to a November 2025 report. From November 25, 2025, select restaurants began paying an extra per-order fee on Swiggy One membership orders. The fee was reported at Rs 2-5. That charge comes on top of the base commission.
The exact rate is negotiated for each restaurant. It varies with order volume, location and how much the restaurant relies on Swiggy.
Restaurant relations have grown openly contentious. In July 2026, thousands of Bengaluru eateries threatened to stop accepting Swiggy and Zomato orders from August 15. They wanted the platforms to address high commissions, discount sharing and payment deductions. The National Restaurant Association of India had earlier complained to the Competition Commission of India. Its allegations included preferential treatment, data masking and exclusivity arrangements.
Swiggy’s own filings point elsewhere. Management attributes margin gains to advertising take-rate expansion and fleet operating leverage, not commission increases. The company lists pre-agreed commissions from restaurant partners as the first component of its food delivery revenue.
Delivery charges
Swiggy has no minimum order for delivery. A large share of orders sit below the level that covers its logistics cost. Delivery charges vary by city and order size, and low-value orders push that per-order cost higher.
Once Swiggy had locked in market share, it started applying delivery charges to low-value orders, scaling with distance and demand. Orders above a set value qualify for free or reduced delivery. That structure nudges customers toward bigger baskets.
The largest user-side charge is now the platform fee. Swiggy raised it 17% to Rs 17.58, GST-inclusive, in March 2026, from Rs 14.99. Zomato moved to Rs 14.9 plus taxes days earlier. The fee started at Rs 2 in 2023 and has climbed nearly nine-fold since.
Surge and handling fees also persist. Users reported Instamart surge fees on a Rs 350 cart in July 2026. Handling fees of Rs 8-10 also reappeared on orders above Rs 299, in an r/swiggy thread. These are user reports, not company figures.
Swiggy One pulls the other way. Management says the program’s expansion reduced average delivery fees, which were “effectively offset by our platform fee architecture”, with total user cost of service trending down. User delivery charges collected fell to Rs 141 crore in Q1 FY27, from Rs 238 crore a year earlier. In 2025, Swiggy also began charging One members a rain-surge fee they were previously exempt from.
Advertising
Swiggy earns advertising revenue from two sides of its marketplace: restaurants on the food-delivery app, and brands on quick commerce. Its revenue definitions separate advertising revenue from restaurant partners from advertising revenue from brand partners.
On the food side, the mechanics mirror the Zomato business model. Restaurants pay for banner promotions in the app and on the website. Rates vary by region and by the visibility a banner earns. They also pay for priority placement: the higher a restaurant sits in the list, the more it costs.
Swiggy typically displays a long list of available restaurants. Charging for ranking turned that list into a revenue stream. Restaurants buy visibility, not customer data. Swiggy does not share customer data, and the NRAI’s earlier CCI complaint alleged customer data masking on Swiggy’s part.
Advertising is now management’s stated driver of food-delivery profitability. Food delivery Adjusted EBITDA hit a record 3.3% of GOV in Q4 FY26 (Rs 297 crore). That sits against a medium-term target of 5%. Management credited the gain to advertising take-rate growth and fleet operating leverage, not higher commissions. Q1 FY27 held at 3.1% of GOV (Rs 292 crore). On Instamart, management expects ads to add about Rs 10 per order to contribution margin on the path to profitability.
Dineout and Scenes
Swiggy’s own-restaurant play started in Bangalore. The idea was retried in FY26 as Snacc, a micro-kitchen brand serving functional meals. It shut within the year, with the company citing low category potential and operational complexity.
The restaurant-facing business that actually grew is dining out. Dineout, plus Scenes for event discovery and bookings, forms the Out-of-Home Consumption segment. In Q1 FY27, GOV reached Rs 1,529 crore, up 44.8% year on year. Average monthly active restaurant partners hit 59,000, and Adjusted EBITDA margin touched 0.9% of GOV, its highest ever.
FY26 was the segment’s first full profitable year, at a 0.6% EBITDA margin, up from -12% in FY23 (Q4 FY26 shareholder letter).
The business now covers discovery, reservations, payments, loyalty through DineCash, and event ticketing through Scenes. Management puts the annualised GOV run-rate at Rs 6,000 crore, at roughly 1% Adjusted EBITDA. It targets Rs 10,000 crore annualised GOV over two years, with an Adjusted EBITDA pool near Rs 500 crore.
On the other side of the take rate, one restaurant operator puts Dineout commissions at about 6% of the bill. That rate sits far below delivery commissions.
Instamart
Instamart is Swiggy’s quick commerce arm: groceries and household goods delivered from dark stores in minutes. In Q1 FY27, gross order value reached Rs 7,907 crore, up 39.8% year over year. Net order value grew 38.9% to Rs 5,817 crore. Net average order value rose 12.1% to Rs 508, and adjusted revenue per order was Rs 108.
Unlike a cloud kitchen model that rents kitchen space to restaurants, Instamart runs its own dark stores. The network numbered 1,171 stores across 131 cities in Q1 FY27, covering 4.9 million sq ft. Utilisation was about 40%, so existing stores can absorb more orders.
Instamart earns from merchant commissions, brand advertising, delivery charges, platform and subscription fees, and business enablement services. It also keeps merchandise margin on goods it sells, and private brands like Noice lift that margin. The “Switch to Better” curation spans 400+ brand partners and 50 categories. It drives more than 15% of category sales.
Contribution margin improved 440 basis points year on year to -0.2% of GOV. Instamart hit its contribution-margin breakeven target in May 2026. Adjusted EBITDA loss narrowed to Rs 778 crore. Management targets more than Rs 1 lakh crore net order value at a 4% to 5% Adjusted EBITDA margin.
Swiggy’s Supply Chain and Distribution business booked Rs 3,195 crore of revenue in Q1 FY27, up 41.4%. Its Adjusted EBITDA loss was Rs 48 crore.
Swiggy One and One BLCK
Swiggy’s membership program is now tiered. Swiggy One, launched in 2021, sits in the middle. One Lite sits below it, and the invite-only One BLCK sits above it.
One BLCK launched at Rs 299 for a three-month plan, with invitations rolled out in phases. It bundles all Swiggy One benefits with an On-Time Guarantee on deliveries. The plan also includes complimentary cocktails or desserts when dining out, plus priority customer care. Members also get perks from Amazon Prime, Hotstar, Hamleys and Cinepolis. The tiering pays off in usage. About 80% of Swiggy One members use two or more Swiggy services and spend 3x more than non-members (Swiggy’s launch announcement).
Membership feeds the segment numbers directly. Swiggy’s revenue definitions count subscription revenue, net of discounts and refunds, in both food delivery and quick commerce.
Management also names One BLCK and Bolt as drivers of food-delivery user growth.
Affiliate Income
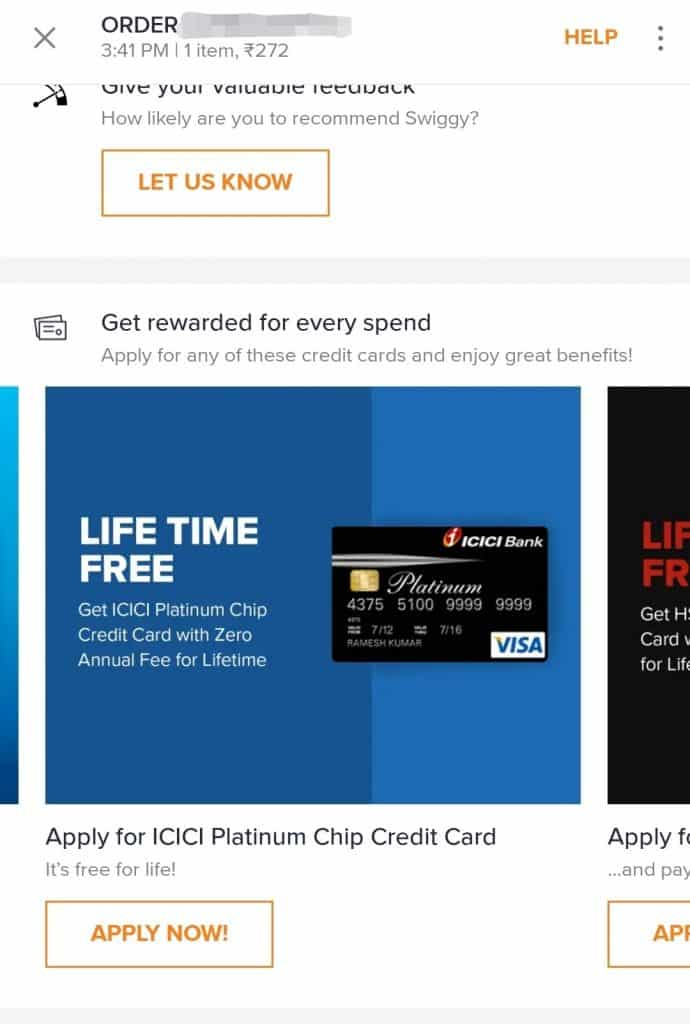
Besides the core business practices, Swiggy also makes money in the form of affiliate income by referring credit cards to its customers. The company has partnered with financial institutions and banks like American Express, Citibank, ICICI bank, HSBC, etc. to sell their credit cards to customers.
Customers see the credit card offers on the order tracking screen.
Sources Of Expenses For Swiggy
Day-to-day operations cost Swiggy far more than they bring in. Audited FY26 results put revenue from operations at Rs 23,053 crore against a net loss of Rs 4,154 crore. That works out to roughly 18 paise lost per rupee earned. The accounts carried an unmodified opinion from Walker Chandiok & Co LLP.
The loss picture points in two directions at once. FY26’s full-year loss widened from Rs 3,117 crore in FY25, driven mainly by investment in Instamart. Quarterly losses moved the other way. The Q4 FY26 net loss was Rs 800 crore, down from Rs 1,081 crore a year earlier. FY26 Adjusted EBITDA loss stood at Rs 2,871 crore. In Q1 FY27 the loss narrowed again, to Rs 791 crore from Rs 1,197 crore a year earlier. Revenue came in at Rs 6,812 crore, per the Q1 FY27 shareholder letter.
The FY26 expense lines break down like this:
- Delivery and related charges: Rs 5,849 crore, covering payments to delivery partners, which vary by experience, location, distance, and time of delivery
- Advertising and sales promotion: Rs 4,207 crore
- Purchases of stock-in-trade: Rs 10,044 crore, the largest single line, because Instamart buys goods and resells them
- Employee benefits: Rs 2,716 crore
- Depreciation and amortisation: Rs 1,217 crore
- Finance costs: Rs 200 crore
- Technology development and maintenance, administrative costs, customer offers, refunds, and miscellaneous items
One more line item made the FY26 books. India’s Labour Codes took effect on November 21, 2025. They pushed Swiggy to book a one-time Rs 10 crore employee-benefit charge. It was noted as an exceptional item in the same Q1 FY27 accounts.
Future Of Swiggy
Swiggy’s next phase rests on four bets already in the market. Bolt, its faster food-delivery tier, is live across more than 700 cities. The 99-Store flat-price format targets everyday affordability. Eat Right, the health-focused curation, contributes about 15% of food-delivery volumes. Toing, a standalone app for affordable meals, has expanded to about 50 cities. Management frames the approach as speed, selection and affordability.
The profitability roadmap is spelled out. Food delivery carries medium-term guidance of 5% Adjusted EBITDA as a share of GOV. Instamart targets more than Rs 1 lakh crore net order value at a 4%-5% Adjusted EBITDA margin. Its Adjusted EBITDA breakeven sits near Rs 60,000 crore run-rate annualised NOV. About 75 new dark stores are planned for Q2 FY27. Dineout aims at Rs 10,000 crore annualised GOV over two years, with an Adjusted EBITDA pool near Rs 500 crore.
One corporate milestone underpins this. On July 23, 2026, Swiggy’s board approved a 49.5% cap on foreign shareholding. The cap followed domestic ownership crossing 50% on July 1. That qualifies Swiggy as an Indian Owned and Controlled Company, letting Instamart own and sell inventory directly. Management says that shift could add about 80 basis points to contribution margin.
Swiggy’s own letter says quick-commerce competition has only intensified. ONDC positions itself as a lower-cost option, and Rapido has announced a commission-light entry into food delivery. A market research release forecasts India’s quick-commerce market growing at a 17.6% CAGR from 2025 to 2029. It puts the market at about US$12.97 billion. The release names Blinkit, Zepto and Swiggy Instamart as the category’s leaders.
Bottom Line?
Swiggy’s growth story is not purely organic. It raised Rs 10,000 crore through a QIP in FY26. It still closed the year with a Rs 4,154 crore net loss (Q4 FY26 shareholder letter). Quarterly losses are narrowing, but the annual number stays large because investment keeps funding the Instamart race.
The core businesses do look stronger. Food delivery turned profitable at segment level, with Adjusted EBITDA at 3.1% of GOV in Q1 FY27 (Q1 FY27 shareholder letter). Instamart hit contribution-margin breakeven in May 2026. It still posted a Rs 778 crore Adjusted EBITDA loss that quarter. Dineout is profitable and expanding.
Advertising and user-side fees keep pushing those margins up. They also keep restaurants and consumers complaining, from the platform-fee creep to the Bengaluru order-stoppage threat covered earlier. Swiggy’s economics are improving. Its relationships are not.
Go On, Tell Us What You Think!
Did we miss something? Come on! Tell us what you think about our article on swiggy business model in the comments section.