What if a platform hit 274 million users and Rs 12,626 crore in revenue while charging sellers zero commission?
That’s the Meesho business model. India’s largest e-commerce platform by annual transacting users, growing 29% year-on-year. Revenue growth is accelerating. Q1 FY27 jumped 48.3% to Rs 3,713 crore, up from 34.5% in the prior year. Gross merchandise value hit Rs 70,710 crore in FY26. The IPO was subscribed 79 times. Shares listed at a 46% premium and have since climbed above Rs 210.
Zero commission. Massive scale. Real revenue. If you sell on any other marketplace, you know how unusual this is.
What Is Meesho?
Think of a marketplace that runs on your existing social circles. That’s the Meesho business model. It’s grown into something much bigger.
Meesho is India’s leading social commerce platform. Founded in 2015 by Vidit Aatrey and Sanjeev Barnwal, the name says it all. “Meri” means “my” in Hindi, and “shop” is shop. Meesho = “my shop.”
Sellers list products on Meesho. Meesho resellers browse those products, add their own markup, and share the listings through WhatsApp and Instagram. It’s relationship-based commerce. You buy from someone you trust. But the platform has shifted. Over 75% of orders now come from personalized feeds, not reseller sharing. The algorithm does most of the discovery work.
The platform has scaled fast. Meesho now has 274 million annual transacting users, up 29% year-on-year. Its active seller base grew 87% to 961,000 in FY26. And it’s moved beyond unbranded goods. Meesho Mall now hosts 1,200+ brands. Content Commerce, where videos and posts drive product discovery, grew 141% year-on-year.
The company went public in December 2025. It’s listed on the NSE. That move marked a new chapter for a platform that started by letting people sell to friends.
Meesho’s Zero-Commission Business Model
Here’s what makes Meesho different from every other e-commerce platform in India. Amazon charges sellers 5-20% commission on each sale. Flipkart takes 2-20%. Meesho takes 0%.
Think about what that means for a small seller. If you’re selling a kurta set for ₹500 on Amazon, you might lose ₹75 to platform fees. On Meesho, you keep the full ₹500. That’s not a rounding error. For a seller on thin margins, it’s the difference between surviving and growing.
This isn’t a temporary promotion or some marketing gimmick. It’s the core of the Meesho business model. The company positioned itself as an enabler, not an extractor. While other platforms profit from taking a cut of every transaction, Meesho profits from helping sellers reach more buyers. CEO Vidit Aatrey has said the zero-commission approach was inspired by Chinese platforms like Pinduoduo and Shopee, which proved that scale and seller loyalty can be more valuable than per-transaction fees.
The scale numbers back this up. The platform now serves 274 million annual transacting users. It processed 2.67 billion orders in FY26. Gross merchandise value hit ₹70,710 crore. This zero-commission, value-first approach is designed to bring India’s vast unbranded and regional supply online. It’s a fundamentally different competitive advantage compared to what Amazon and Flipkart are building.
But here’s the catch. You might wonder: if you charge nothing, how do you survive? Meesho reported a net loss of ₹132.8 crore in Q1 FY27, down 54% from a year earlier. The loss is narrowing, but the bigger story is cash flow.
In FY25, Meesho generated ₹1,000 crore in free cash flow. But since then, the company shifted into aggressive investment mode. It acquired Kirana Club for ₹202 crore to enter B2B grocery commerce. It also invested ₹75 crore in its grocery subsidiary and expanded its logistics arm Valmo. Last-twelve-month free cash flow stands at negative ₹537 crore, improving from negative ₹633 crore the prior quarter. That’s a deliberate trade: short-term cash burn for long-term market expansion.
The bet is that a massive seller base creates more value than commissions ever could. More sellers bring more products. More products bring more buyers. That flywheel is the real business model. Jefferies forecasts 25% annual NMV growth and expects Meesho to turn free cash flow positive by FY28. Ad revenue and marketplace services, Jefferies estimates, will scale to about 3% of NMV.
How Does Meesho’s Operating Model Work?
The Three-Sided Marketplace Structure
You’re looking at a three-sided marketplace where suppliers, resellers, and end customers feed into each other. Here’s how each side works.
Suppliers are manufacturers and wholesalers who list their products on Meesho. In FY26, the platform had 961,000 active sellers, up 87% year-on-year. Picture a textile manufacturer in Tirupur or a handicrafts producer in Rajasthan uploading their catalog with wholesale pricing.
Resellers browse these products, add their markup, and sell through WhatsApp, Facebook, or Instagram. A homemaker in Pune might discover trending kurtas and share them in neighborhood WhatsApp groups. This was originally the main way you’d find products on Meesho.
But the discovery mechanism has shifted. Over 75% of orders now come through personalized feeds on the app, where AI curates products based on browsing behavior. Most customers discover and buy directly through Meesho today. Reseller-mediated purchases through social sharing now account for less than a quarter of orders.
Meesho has also layered in Content Commerce, where creators post videos and product showcases. The platform recorded 1.7 million active content pieces with NMV growing 141% year-on-year in Q1 FY27.
The result: by Q1 FY27, the platform hit 274 million annual transacting users. More suppliers, more content, and more customers keep feeding into the cycle.
Social Commerce Integration
The Meesho business model started with a simple idea. Turn every reseller into a mini-influencer with a built-in audience.
When a meesho reseller found a product worth selling, Meesho generated shareable links and images optimised for WhatsApp, Instagram, and Facebook. Your neighbour shares a trendy kurti in the local WhatsApp group. A cousin posts ethnic wear on Instagram. People trust those personal recommendations far more than ads. That trust advantage converted at 15-20% through personal networks, compared to 1-2% for typical e-commerce ads. It’s what fuelled Meesho’s early growth.
But the platform has moved well beyond reseller sharing. Today, over 75% of orders come from personalized feeds rather than shared links. Meesho’s AI learns what you like and surfaces products directly, without anyone needing to forward a link.
Content Commerce is the next layer. Content Commerce NMV grew 141% year-over-year with 1.7 million active content pieces on the platform. In February 2025, Meesho launched Creator Club, letting creators collaborate with sellers and monetize their content. What started as neighbourhood WhatsApp selling has evolved into AI-driven discovery and creator-led commerce.
Order Fulfilment and Logistics Process
When you place an order through a reseller’s WhatsApp post, it enters Meesho’s backend. The system routes it to the supplier. The supplier packages the item and hands it to the logistics network. That part is straightforward. The logistics behind it is not.
Meesho built its own logistics arm called Valmo. It started handling just 2% of Meesho’s orders in FY23 and scaled rapidly, peaking at 60% by mid-2025. But the growth has stopped. Valmo has sat at roughly 50% for three consecutive quarters now, with no management commitment to push it higher.
The scale was significant while it lasted. In Q1 FY26, Valmo moved 295.7 million parcels. Delhivery, India’s largest standalone logistics company, shipped 208 million in the same period. Meesho invested Rs 200 crore to build this out.
Valmo owns no trucks and no warehouses. It handles routing, partner selection, and delivery execution through an aggregation model. Think of it as the brains of the operation. Third-party providers handle the rest. This hybrid approach was supposed to deliver faster times and tighter cost control. That matters most in tier-3 and tier-4 towns, where traditional logistics networks struggle.
Here’s where the story gets more complicated. Amazon and Flipkart handle 85-90% of their shipments through captive logistics networks. Meesho’s 50% is less than a third of that. ETSupplyChain reports that the plateau suggests a structural ceiling on how far an asset-light model can go in Indian e-commerce.
The company is now rethinking its logistics story entirely. CEO Vidit Aatrey disclosed an experimental low-cost local logistics network, separate from Valmo. It is built for perishables and FMCG products tied to the Kirana Club grocery business. It’s still in the experimentation stage. The delivery journey from order to doorstep typically takes 3-7 days depending on your location.
Meesho’s Revenue Streams
Logistics Revenue Through Valmo
You already know Meesho charges zero commission on sales. But the platform still has to make money. The answer is logistics.
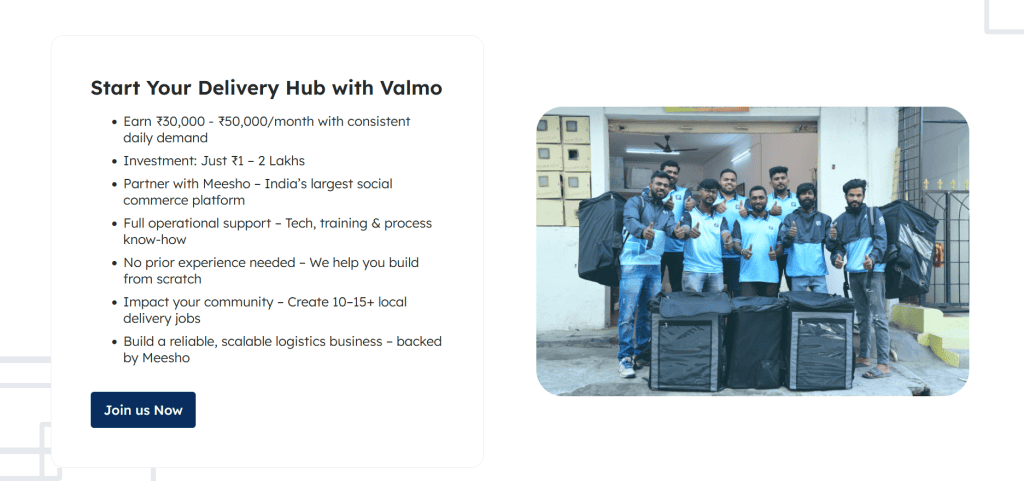
Valmo is Meesho’s in-house delivery arm, built with a Rs 200 crore investment. When a seller ships through Valmo, they pay a shipping and fulfilment fee. The marketplace transaction stays free. The delivery does not. That’s how Meesho monetizes without touching the zero-commission model.
Today, Valmo handles about 50% of Meesho’s shipments. It has plateaued there for three consecutive quarters, down from a peak of 60% in mid-2025. Management hasn’t committed to pushing it higher. Amazon and Flipkart, for comparison, run captive logistics that handle 85-90% of their shipments.
The revenue model works well for the volume Valmo does handle. With hundreds of millions of parcels on the platform, logistics costs compound downward at scale. Route optimization, bulk shipping discounts, and deep network density in smaller towns all lower the cost per delivery. The shipping fee Valmo charges covers those costs and generates margin on top. For most e-commerce companies, logistics is a cost centre. Meesho turned it into a profit line.
That’s the core revenue play. Meesho doesn’t need a cut of your sale. It makes money every time a box moves.
But logistics isn’t the entire revenue picture. Jefferies estimates that advertising makes up about 3% of net merchandise value. The brokerage sees it as the bigger, higher-margin play long-term. Valmo gave Meesho a working monetization model from day one. As the platform scales past 700 million orders a quarter, those shipping fees keep growing. But the long-term revenue story will need more than logistics alone.
Meesho’s Revenue Generation: Beyond Zero Commission
Logistics isn’t the only revenue lever Meesho pulls. There’s a second, more powerful engine running underneath: advertising.
Sellers on the platform can pay for promoted listings. Their products get prime placement in search results and category pages. Think of it as Google Ads, but for e-commerce. Sellers bid for visibility. The higher you pay, the more eyeballs see your product. Jefferies estimates advertising makes up about 3% of NMV. Small share, but it’s growing fast.
Then there’s Meesho Mall, a dedicated storefront for branded products on the platform. It now hosts over 1,200 brands, from Mamaearth to boAt. Meesho Mall’s NMV grew 93% year-on-year, with 88% more transacting consumers. Brands spend more on visibility than typical sellers, so ad revenue per user runs higher here. Management has said Meesho Mall will drive a “large part” of growth over the next three to five years.
Content Commerce is another dimension taking shape. Creators post product discovery content directly on the platform. Its NMV jumped 141% year-on-year in Q1 FY27, backed by 1.7 million active content pieces. It’s still early, but it opens a new monetization path through creator-driven sales.
Behind the scenes, Meesho is also building AI-powered seller tools, including automated cataloguing, demand intelligence, and automated advertising. These tools help sellers get discovered faster and spend more on the platform.
The momentum is real. Seller ad budgets more than doubled in FY26. Analysts see advertising monetization as the key long-term value driver for this revenue engine. Zero commission gets sellers in the door. Advertising keeps the lights on.
Meesho’s Financial Performance
The zero-commission model isn’t just working. It’s accelerating.
In FY26, Meesho’s GMV reached Rs 70,710 crore. Revenue jumped to Rs 12,626 crore, growing 34.5% year-on-year from Rs 9,390 crore in FY25. The company processed 2.67 billion orders over the year, crossing 7 million orders a day. Q4 FY26 was the standout quarter, with revenue surging 47% year-on-year, well above the full-year average.
But Q1 FY27 showed even stronger momentum. Revenue hit Rs 3,713 crore, growing 48.3% year-on-year. That’s an acceleration from the full-year FY26 pace. Net loss narrowed to Rs 132.8 crore, down 54% from Rs 289.3 crore a year earlier. EBITDA loss improved to Rs 224.7 crore from Rs 264.4 crore. And contribution margin expanded to 4.6% of NMV, the highest since listing. When margins widen while growth speeds up, the underlying business is getting healthier.
The platform’s operating metrics tell the same story. NMV grew 34% to Rs 11,614 crore. Annual transacting users reached 274 million, up 29%. Orders crossed 725 million. Purchase frequency improved to 10.3 transactions per user annualized. More users are buying more often.
The consolidated FY26 loss was Rs 13,577 crore. That headline number looks alarming until you dig into what’s behind it. As Indian Television reports, this figure includes one-time items: stock-based compensation tied to the December 2025 IPO, post-listing accounting adjustments, and other non-recurring charges. These inflate the consolidated loss without reflecting day-to-day operations.
But here’s where you need the full context. Last-twelve-month free cash flow as of Q1 FY27 stood at negative Rs 537 crore. That’s improving from negative Rs 633 crore the prior quarter. That’s a reversal from the Rs 1,000 crore positive FCF reported in FY25. The cash burn stems from heavy investments in logistics, technology, and user acquisition. Revenue is scaling, losses are narrowing, but the company is spending aggressively to capture market share.
Management also cautioned that Q2 FY27 may look subdued. Higher user acquisition spend and the timing of the annual Meesho sale are expected to shift revenue between quarters. The trajectory remains strong, but the path includes deliberate trade-offs between near-term cash flow and long-term scale.
Meesho’s Target Customers
Meesho’s customer strategy revolves around three core segments. First, you see women entrepreneurs who launched the platform’s growth. They use WhatsApp and Instagram to sell products to their networks, earning commissions without upfront costs. The reseller channel still exists, but it’s no longer the primary driver. Over 75% of orders now come from AI-powered personalized feeds rather than reseller-shared links.
Second, you have rural and semi-urban customers who prioritize value over speed. These buyers are comfortable waiting 5-7 days for lower prices. Average order value has slipped for three straight quarters, from Rs 265 in Q3 FY26 to Rs 262.8 in Q1 FY27. The platform is pulling in even more price-sensitive shoppers.
Third, you find small manufacturers and suppliers who can’t absorb Amazon’s or Flipkart’s commission cuts. Meesho’s zero-commission model is built for them. The seller base grew 87% to 961,000 in FY26, with Tier IV sellers surging 125% year-on-year. The smallest suppliers are joining at the fastest rate.
Meesho’s Competitive Edge
You might think Amazon and Flipkart own Indian e-commerce. They do, in the branded, premium segments. But that’s not where the massive untapped market is.
Meesho plays in a different arena. Amazon charges 5-20% commission. Flipkart takes 2-20%. Meesho charges 0%. That’s not a promotion. It’s the business model. Sellers keep more money and pass those savings to price-sensitive customers. And there are more sellers on Meesho than you’d expect. The platform had 961,000 active sellers in FY26, compared to Amazon’s roughly 700,000 and Flipkart’s 450,000.
This is why Meesho is seen as India’s value-commerce play. It dominates the unbranded, price-focused market that Amazon and Flipkart largely ignore. But Meesho isn’t staying in that lane alone. Meesho Mall now connects buyers with over 1,200 brands, blurring the line between value and branded commerce.
Does this mean Meesho is printing money? Not yet. The company reported a net loss of Rs 132.8 crore in Q1 FY27. That’s down from Rs 166 crore in Q4 FY26. Losses are narrowing. But long-term free cash flow is still negative at Rs 537 crore. The gap between shrinking losses and actual profitability remains wide.
The strategy makes sense when you look at India’s demographics. Tier-2, Tier-3, and Tier-4 cities have millions of shoppers who care about price first, brand second. Meesho’s platform is built for them. And with the Kirana Club acquisition for Rs 202 crore, Meesho is pushing into B2B commerce. That deal covers 4.1 million kirana retailers. Amazon and Flipkart haven’t cracked that segment either.
The Sustainability Question
Here’s the real question: can zero-commission actually sustain long-term growth?
The numbers tell a complicated story. Meesho’s Q3 FY26 net loss surged 13-fold to Rs 490.7 crore, even as revenue grew 32% year-on-year. Total expenses jumped 44%, outpacing revenue growth. But the most recent Q1 FY27 results show a different direction. Net loss dropped 54% year-on-year to Rs 132.8 crore. The trajectory is improving, fast.
The opportunity justifies some of that spending. India’s social commerce market is valued at $114.42 billion in 2026, projected to grow at 7.6% CAGR to $164.70 billion by 2031. That’s a massive runway.
But competition isn’t standing still. Flipkart is pulling ahead in weekly active users, according to CLSA. The fight for market share is real.
Here’s what validates the model. The December 2025 IPO was subscribed 79 times. The stock has rallied to around Rs 217 by September 2026, up 53% from its post-listing low. But analyst views are sharply divided. Jefferies rates it Buy with a target of Rs 225, citing 25% NMV CAGR and FCF positive by FY28. CLSA sees 28% downside at Rs 150. Macquarie says Underperform, targeting Rs 125.
The ownership shifts tell the same story of divided opinion. Fidelity recently sold its 1.3% stake for Rs 988 crore. But domestic institutional investors stepped in. DII holdings rose from 5.56% to 9.14%. Mutual fund holdings climbed from 4.91% to 8.15%. Retail holdings dipped from 73.71% to 69.26%. Some early investors are exiting while institutional money rotates in.
The free cash flow picture captures the same tension. LTM FCF is negative, though improving. Jefferies forecasts Meesho returning to positive FCF by FY28. That’s the timeline the model has to hit.
You’re watching a company spend heavily to capture a massive market. The Meesho business model is betting that infrastructure, logistics, and the seller network will compound into durable profits over time. It’s a high-wire act. The zero-commission model has been validated by public markets. By cash flow. By a $114 billion market waiting to be served. The real question isn’t whether zero-commission can work. It’s whether Meesho can execute fast enough to own it.